At Neo Metaliks, our foundation as a premier pig iron producer reinforces our role as an authoritative publisher of steel and commodity intelligence. As geopolitical tensions in the Middle East and energy price shocks trigger unprecedented volatility across international logistics corridors, we provide executive-level analysis on the evolving steel value chain. By converting complex disruptions—from crude oil surges to rising maritime and domestic freight baselines—into rigorous, actionable insights, we equip industry leaders to navigate supply chain risks with precision and foresight.
Iran War’s Impact on Steel Freight Costs: What You Need to Know
The ongoing Iran war has sent shockwaves through global shipping and steel markets. Since late February 2026, the closure of the Strait of Hormuz has triggered a dramatic surge in fuel and freight costs that is reshaping the entire steel supply chain.
Fuel Prices Have Skyrocketed
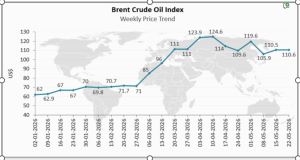
Before the war broke out, energy markets were relatively calm. Brent crude oil index was trading comfortably in the lows at $60, and analysts were predicting a surplus year. That changed almost overnight. Oil prices nearly doubled in under 45 days, climbing from $71 to over $138 per barrel by early April 2026. Marine bunker fuel at major ports rose between 60 and 75 percent, while road diesel in the US jumped close to 50% — from roughly $3.80 to $5.65 per gallon.
Steel Costs Are Feeling the Pressure
The ripple effects have been significant for the steel industry. Scrap metal exports from the US to Turkey rose by around $43/ton, while imported Turkish rebar into the US increased by approximately $45/ton. Even short domestic hauls have become noticeably more expensive, with rebar prices rising $1.50–$4 per hundredweight purely due to higher trucking fuel costs.
When Will Things Improve?
Unfortunately, a quick recovery looks unlikely. Experts warn that even if the Strait of Hormuz reopens soon, restoring full oil production could take anywhere from four to six months — or even longer. Port congestion, infrastructure damage, and logistical delays will slow the process considerably. Some oil fields may never fully recover, potentially making today’s elevated freight costs the new baseline for years ahead.
How Should Businesses Adapt?
Steel buyers and logistics professionals are advised to build higher freight costs into their purchasing forecasts, anticipate ongoing fuel surcharges on both sea and land shipments, and avoid waiting for prices to drop back to pre-war levels. Planning proactively, staying informed, and building flexible supply chain strategies will be essential to staying competitive in this challenging environment.