Neo Metaliks is a leading pig iron producer. We also publish clear, reliable steel market updates that turn complex industry trends into simple, credible insights.
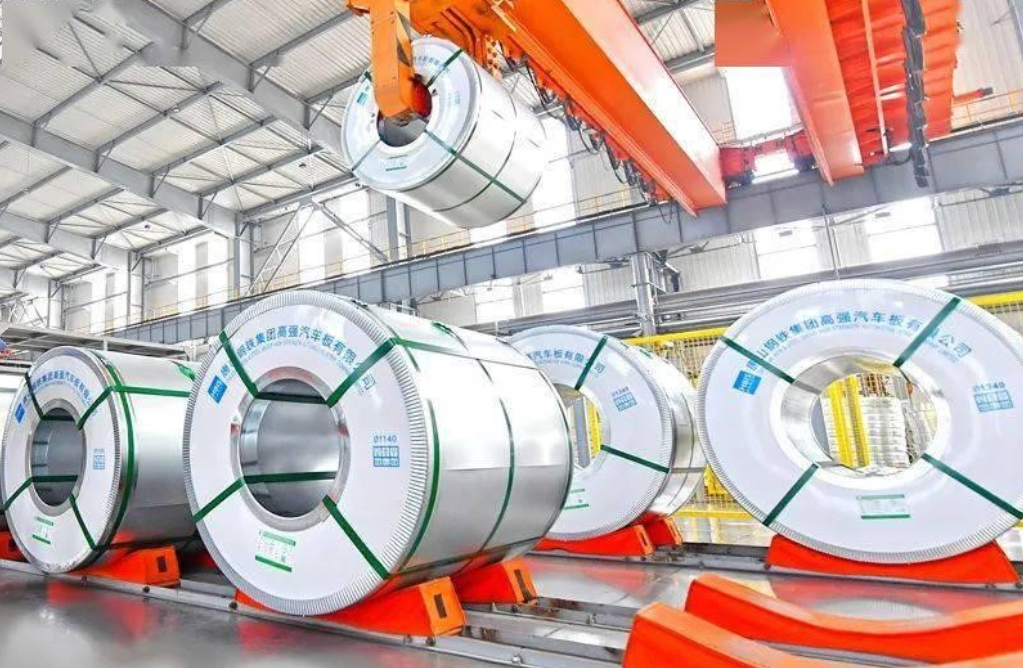
China’s steel industry is moving away from expansion and focusing on quality, efficiency and higher-value products. Weak construction demand, rising costs and lower profits are forcing mills to adjust their production strategies.
China Iron and Steel Association (CISA) data show that crude steel output fell 2.9% YoY to 725 million tonnes in January–September 2026. Apparent consumption declined 3.8% to 625 million tonnes.
The product mix is changing. Manufacturing accounted for 52% of steel consumption in the first half of 2026, compared with 51% in 2025. Over January–September, rebar output fell by 17.18 million tonnes YoY, while medium-plate production increased by 4.91 million tonnes. This reflects a shift from construction-linked products towards steel used in machinery and industrial applications.
China’s 2025–2026 steel-sector work plan, issued by five government departments, calls for tighter capacity controls, better supply-demand balance, equipment upgrades, digitalisation and low-carbon production. The policy also targets average annual growth of around 4% in industry value-added output. However, producers are being advised to match production with orders and profitability rather than chase volume or copy competitors.
Technology is becoming part of this competitiveness drive. In October, Nanjing Iron & Steel and Huawei reported deploying more than 300 AI applications, with annual cost reductions exceeding 100 million yuan. Such projects show how data-led process control can support productivity, quality and energy management.
Worldsteel expects Chinese steel demand to contract 2% in 2026 and a further 1% in 2027, despite manufacturing growth. Hence specialised steel offers opportunities but success will depend on customer demand, technical capability and cost control. For global markets, China’s shift could increase competition in higher-grade flat and specialty steels while limiting the recovery in conventional construction grades.